
Mortgage Payment Calculator
Estimate a monthly mortgage payment with down payment, taxes, insurance, and HOA costs.
Open toolCompare renting and buying under an entered cash-cost scenario. Review financing, ownership costs, rent increases, and assumed sale proceeds over your horizon.
Update the inputs to see your result.
Result will appear here
Two cash-cost models are compared over the same entered horizon.
Buying cash cost adds down payment, closing costs, mortgage payments, and selected running costs, then subtracts assumed sale proceeds after costs and remaining debt. Renting cash cost sums annual rent with the entered yearly increase.
A simplified cash-cost comparison. It excludes investment returns on cash, tax deductions, rent deposits, utilities, moving costs, inflation in ownership costs, and transaction timing. Do not use it alone for a housing decision.
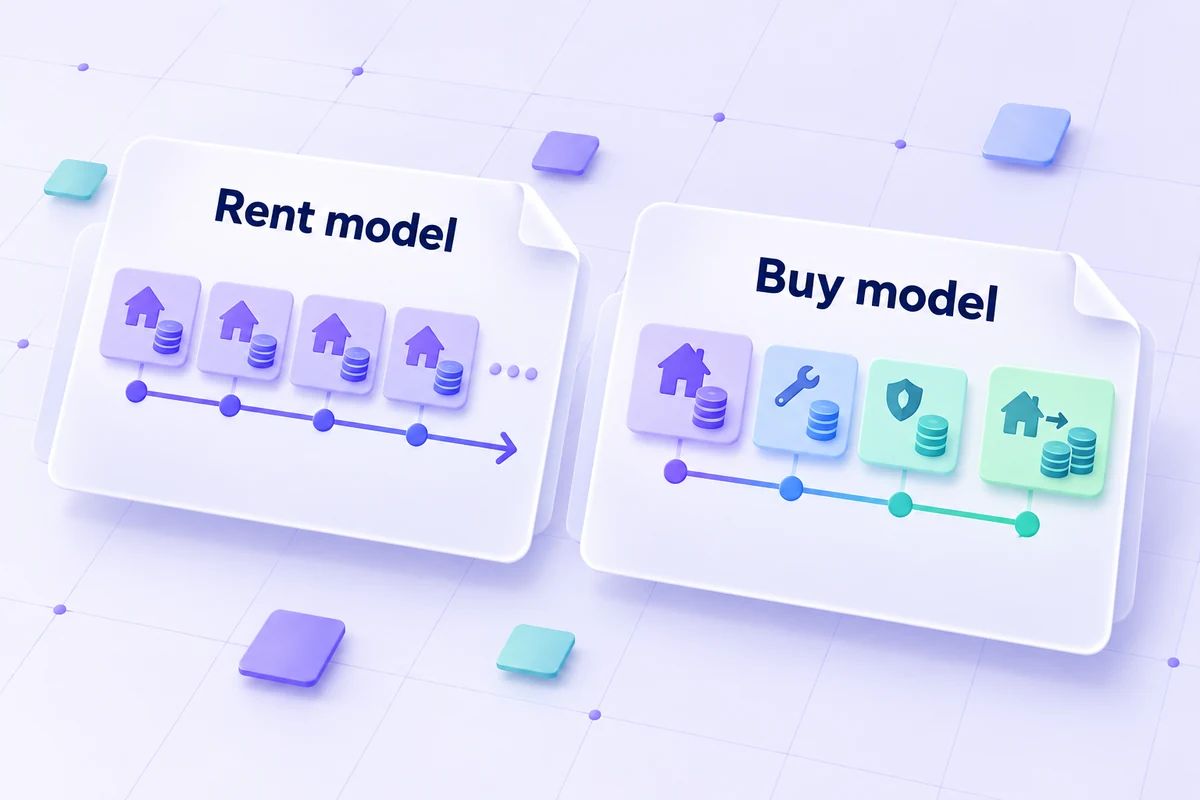
Prepare the purchase, ownership, sale and rental assumptions on matching time periods.
Enter home financing, the comparison horizon, starting rent and rent growth, ownership costs, closing costs, appreciation, and sale costs. Keep annual expenses separate from monthly HOA. The down payment cannot exceed home price, and the horizon is entered in whole years.
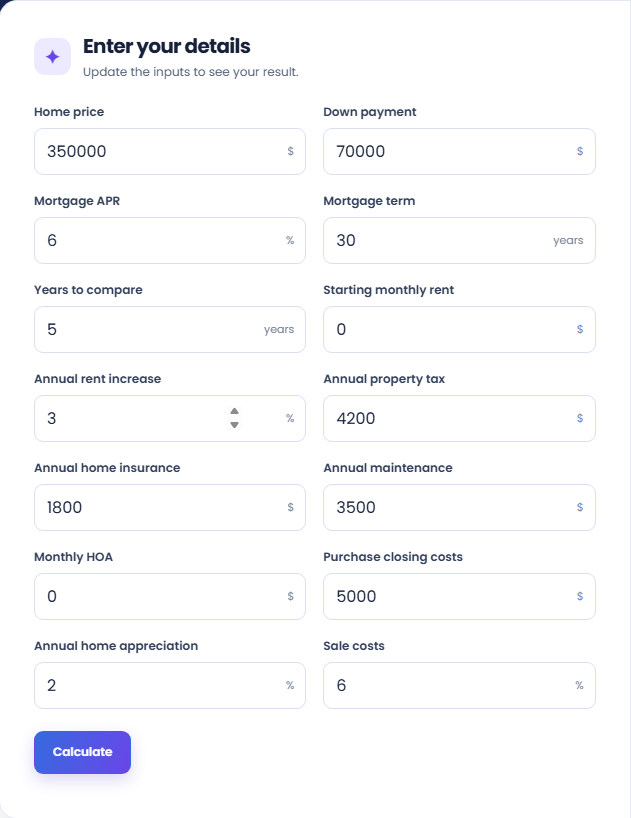
Select Calculate and read which entered scenario has the lower estimated cash cost. The page totals each model over the same horizon. The result depends on the supplied assumptions and is not a forecast or a complete housing decision.
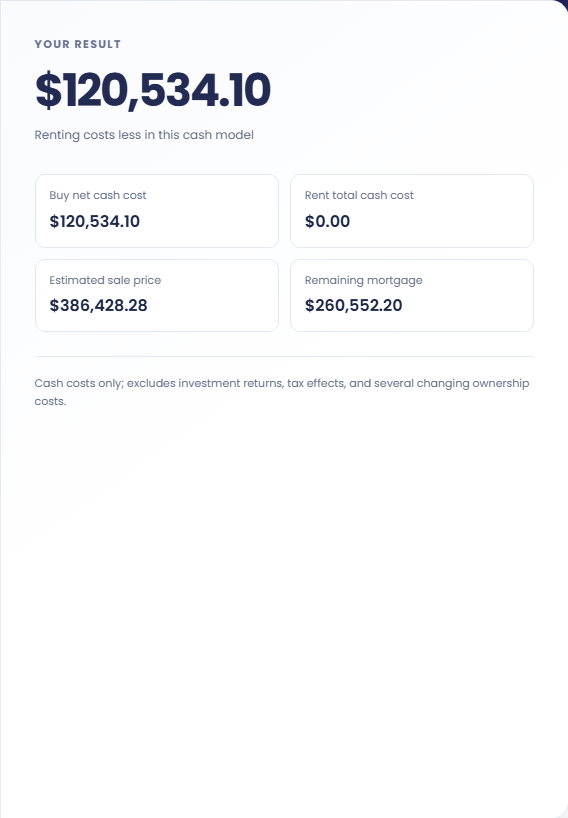
Read Buy net cash cost, Rent total cash cost, Estimated sale price, and Remaining mortgage. Sale proceeds after costs and debt reduce the buying model. Investment returns, tax effects, transaction timing, and several changing ownership expenses are excluded.
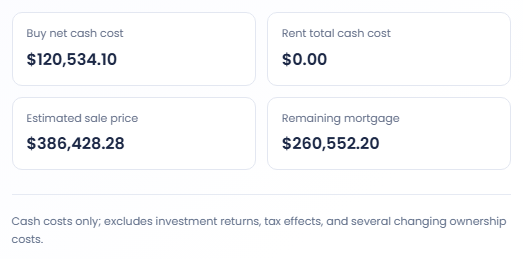
The model compares entered cash costs and does not determine an individual's housing choice.
Keep the purchase, rent and cost assumptions fixed while changing years to compare. Review the sale price and remaining mortgage for each run. This shows how the model's chosen endpoint changes the comparison without predicting what will happen to a real property.
Run the same scenario with different assumed appreciation rates and compare net buying costs. The output reflects the sale proceeds under each assumption. Treat those rates as scenarios rather than evidence of future property values or a reason to prefer one outcome.
Check annual tax, insurance and maintenance against the monthly HOA input before judging the main difference. The model keeps those amounts constant across the entered years. It cannot infer future repairs, cost changes or the actual arrangements of a particular home.
Read the buying total with assumed sale proceeds and remaining debt.
Buying cost includes the down payment, closing costs, mortgage payments and entered running costs, less estimated sale proceeds after selling costs and remaining debt. It is a net cash model, so sale assumptions belong with the cost figure.
The comparison excludes investment returns on cash, tax effects, rental deposits, utilities and moving costs. It also does not model inflation in ownership expenses. A displayed cost advantage cannot settle a housing decision on its own.
Review omitted costs and scenario assumptions before using the comparison.
The down payment cannot exceed the price, and the mortgage term and comparison years use whole years. Review whether annual expenses and monthly charges reached the correct fields before treating a surprisingly large difference as a finding.
Rent growth and home appreciation are entered assumptions. The calculator does not retrieve a market forecast or compare local properties. Keep uncertainty and costs outside the model in your review of any actual housing choice.
Estimate a monthly mortgage payment with down payment, taxes, insurance, and HOA costs.
Open tool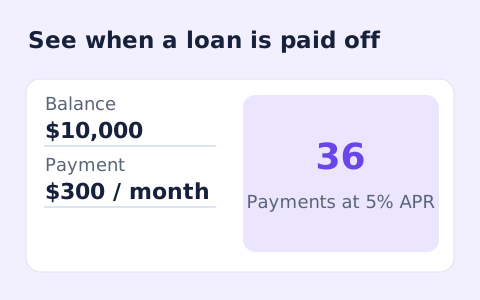
Estimate loan payoff time and interest savings from regular and extra monthly payments.
Open tool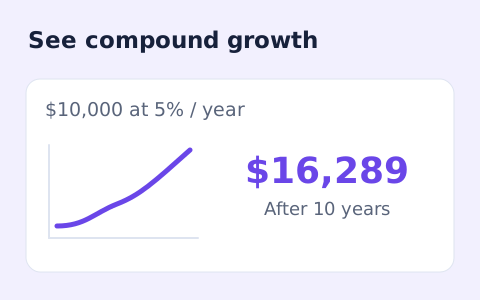
Estimate compound growth from a starting balance, monthly contribution, annual rate, and compound frequency.
Open toolChoose another tool for your next calculation, conversion, or text task.
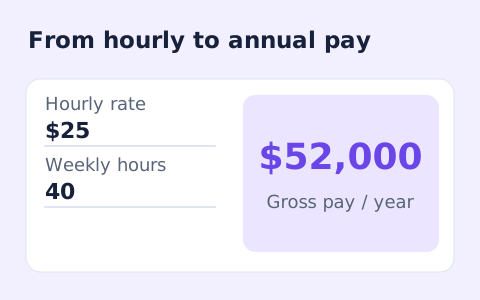
Convert hourly pay to gross annual, monthly, and weekly salary using your own working hours and weeks.
Open tool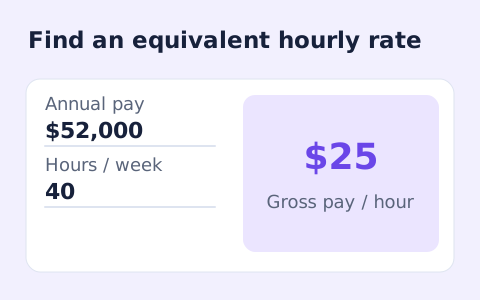
Convert annual gross salary into an hourly rate from your hours per week and paid weeks per year.
Open tool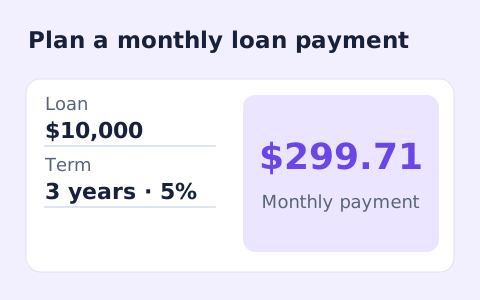
Calculate fixed monthly payments on an amortizing loan using amount, annual rate, and term.
Open tool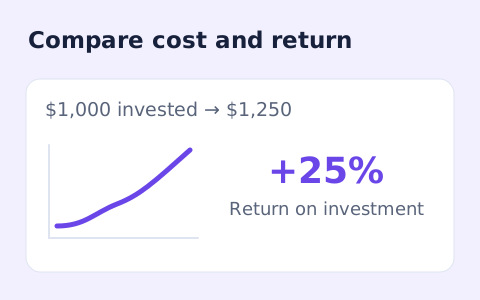
Calculate simple return on investment from the initial cost, final value, additional income, and costs.
Open toolAnswers about using Rent vs Buy Calculator and understanding its results.
Yes. The estimated sale proceeds minus the remaining mortgage balance reduce the buy-side net cash cost.
No. Appreciation is an assumption you enter, not a forecast.
No. It is a cash-cost comparison and omits investment opportunity cost, tax effects, several changing ownership costs, and transaction timing.
The entered property tax, insurance, maintenance, and HOA amounts are held constant in this model. Rent increases and home appreciation use separate entered assumptions.
Compare renting and buying under an entered cash-cost scenario.